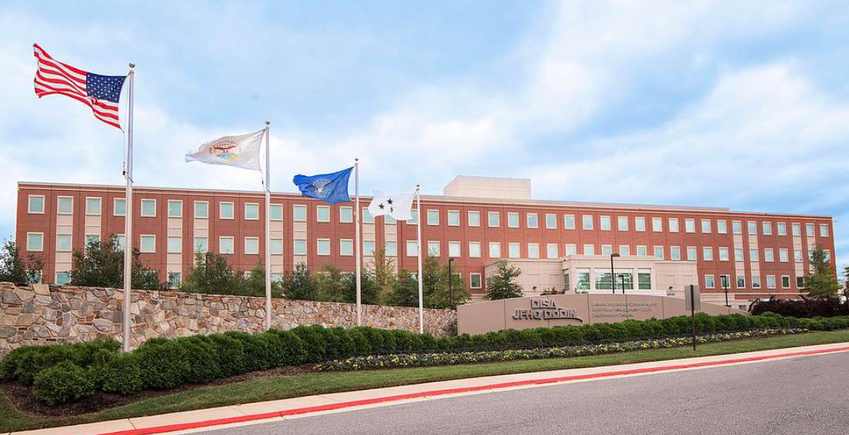
The Defense Information Systems Agency has released the first of two planned solicitations for the Pentagon’s next major enterprise cloud contract, beginning a procurement that could reshape how the Defense Department buys infrastructure, platforms, software and related cloud services over the next decade.
The solicitation covers the Joint Warfighting Cloud Capability Unified Cloud Marketplace Core, or JWCC UCM Core. According to procurement details reported by Washington Technology, the indefinite-delivery, indefinite-quantity contract has a ceiling of $21.6 billion and a potential 10-year ordering period consisting of a five-year base and one five-year option.
Bids for the Core contract are due Oct. 6 at noon Eastern. A separate solicitation for JWCC UCM Premier is expected in the first quarter of calendar year 2027, with awards targeted for the third quarter.
From four hyperscalers to a broader marketplace
The current JWCC contract was awarded in 2022 to Amazon Web Services, Google, Microsoft and Oracle. It gave the department a multiple-award alternative to the canceled, single-provider Joint Enterprise Defense Infrastructure procurement.
JWCC UCM Core would preserve a role for large cloud service providers while expanding the range of products the department can acquire. The solicitation encompasses infrastructure as a service, platform as a service, software as a service and other consumption-based technology offerings described as “anything as a service.”
The planned Premier component would add two more supplier tiers. One would focus on SaaS and PaaS providers, along with infrastructure providers that do not operate at hyperscale. Another would create a route for commercial technology companies and small businesses to offer specialized products.
That structure matters because defense cloud requirements increasingly extend beyond raw compute and storage. Mission owners may need data platforms, cybersecurity tools, software-development environments and applications that operate across enterprise, tactical and disconnected settings. A marketplace model could give them more choices without requiring a separate procurement for every capability.
It could also create a clearer path for smaller vendors that have struggled to enter a market dominated by the four existing prime contractors. The practical effect, however, will depend on how DISA qualifies suppliers, integrates their services and handles ordering across the Core and Premier tiers.
A larger ceiling, but spending will follow task orders
The $21.6 billion figure is a contract ceiling rather than a guaranteed expenditure. Actual spending will depend on task orders issued by military services, combatant commands and Defense Department agencies. Under the current JWCC vehicle, obligations have reached about $1 billion, with AWS and Microsoft receiving most of that work, according to GovTribe data cited by Washington Technology.
The successor procurement arrives as the department works to standardize cloud access while retaining competition among providers. A longer ordering period may give the government and vendors more stability, but it also raises questions about keeping the marketplace current as cloud pricing, artificial intelligence services and security architectures change.
Contract structure alone will not eliminate the operational challenges of moving defense workloads to the cloud. Agencies will still need to address data classification, identity management, interoperability, cost controls, vendor concentration and the ability to shift workloads when mission needs change. The inclusion of more suppliers may broaden competition, but it may also increase the complexity of integrating and governing services across the department.
The immediate development is the opening of competition for the Core tier. The more consequential change will come when the Premier solicitation shows how far the Pentagon is prepared to extend the marketplace beyond the largest cloud providers. Together, the two procurements could determine whether the next phase of JWCC becomes a broader technology ecosystem or remains primarily a vehicle for hyperscale cloud capacity.